India Is Winning the China+1 Shift Just Not Where Most Investors Are Looking
ndia is gaining from China+1 in pharma, chemicals, and electronics, but lagging in labor sectors. The opportunity is not broad-based; it is a selective, sector-level advantage.
India is capturing a meaningful share of the global manufacturing shift away from China. But not in the sectors most investors instinctively associate with that shift.
The real story is more selective and far more investable.
Across pharmaceuticals, specialty chemicals and electronics, India is building durable export positions into Southeast Asia and beyond. In textiles, furniture and consumer goods, the traditional engines of export-led industrialisation, it is steadily losing ground to Vietnam, Bangladesh and Indonesia.
This divergence is not anecdotal. It is visible in bilateral trade flows between India and ASEAN from 2022 to 2025, based on data from the Directorate General of Foreign Trade, the ASEAN Secretariat and external sector trends tracked by the Reserve Bank of India.
The implication is clear: China+1 is not a rising tide. It is a sorting mechanism.
And India is being sorted by sector.
What’s Working: India Is Winning Where Capability Compounds
“India’s export gains are clustering in sectors where switching costs are high.”
At a macro level, India–ASEAN trade has expanded to roughly $120–125 billion by FY2024–25. But the composition of that trade reveals more than the headline number.
India’s exports to ASEAN: ~$39 billion (down from ~$44 billion in FY2022–23)
India’s imports from ASEAN: >$80 billion
Trade deficit: ~$45.2 billion
The widening deficit is real. But it masks a more important shift: India is gaining share in specific high-barrier categories even as it loses ground in others.
Pharmaceuticals: From Alternative to Default
India’s pharmaceutical exports into ASEAN have grown steadily, reinforcing its position as a core supplier of generics and formulations.
This is no longer a price play. It is a trust and compliance play.
Indian firms operate within globally recognized regulatory frameworks US FDA, WHO GMP that create high entry barriers. Increasingly, they are also localizing production within ASEAN markets to bypass non-tariff barriers and deepen market access.
Companies such as Sun Pharmaceutical Industries and Dr. Reddy's Laboratories have expanded their footprint across markets like Vietnam and Malaysia, embedding themselves into regional supply chains.
A healthcare analyst tracking ASEAN procurement flows noted: “In several categories, Indian pharma isn’t replacing China gradually. It has already replaced it.”
That distinction from “alternative” to “default” is the clearest signal of structural gain.
Specialty Chemicals: Sticky Share Gains
India’s specialty chemicals sector continues to compound quietly.
Driven by global diversification away from China’s environmentally constrained production base, Indian exports in agrochemicals, dyes and intermediates have grown at sustained double-digit rates.
These are industries where:
Qualification cycles are long
Switching costs are high
Process engineering matters more than labor arbitrage
As a result, India’s gains are not cyclical. They are sticky.
Analysts at Kotak Institutional Equities note that once a supplier is validated in chemical value chains, “the probability of displacement is low unless there is a material failure.”
Electronics: From Assembly to Strategic Substitution
Electronics is where the China+1 narrative becomes most visible and most misunderstood.
India’s electronics exports: ~$47–48 billion (2025)
Mobile phone exports: projected ~$35 billion in FY2025–26 (up from ~$24 billion in FY2024–25)
The scale-up is undeniable. But the nature of that scale-up has evolved.
The earlier characterization of India as an “assembly-led” exporter is now only partially true.
In Q2 2025, India overtook China to become the largest smartphone exporter to the United States, a milestone driven by the rapid expansion of Apple and Samsung manufacturing bases.
This marks a shift from participation to substitution in at least one major market.
Companies such as Tata Electronics are increasingly positioning themselves within deeper value chains, even as upstream component ecosystems remain underdeveloped.
The signing of new trade arrangements, including expanded market access through bilateral agreements, is further accelerating this shift.
A Mumbai-based industrials investor framed it succinctly: “Electronics is no longer just India’s most visible China+1 story. It’s becoming its most credible one.”
What Isn’t: India Is Losing the Scale Game
“In labor-intensive manufacturing, ASEAN is still the default choice.”
The sectors where India is underperforming are not peripheral. They are foundational to the classic Asian industrialisation model.
Textiles and Apparel: The Gap Persists Even as It Narrows
Vietnam’s apparel exports: ~$46 billion
India’s apparel exports: ~$15.7 billion
The gap remains vast.
India’s apparel exports have grown modestly, but not at the pace required to capture China+1 reallocation. ASEAN trade flows show continued dependence on imports for certain textile categories, alongside stagnant export growth.
Operational constraints persist:
Lower labor productivity
Fragmented manufacturing base
Lead times still averaging 45–60 days, though improving
There is, however, a shift underway.
Integrated textile parks under schemes like PM MITRA have begun compressing lead times toward ~40 days in certain clusters. This is the first sign of structural improvement, but it is not yet system-wide.
A sourcing executive based in Singapore observed: “India is finally fixing speed. But until that becomes consistent across suppliers, global buyers will hedge with Vietnam and Bangladesh.”
Furniture and Consumer Goods: The Cluster Deficit
Vietnam’s rise in furniture exports is not incidental. It is engineered.
Dense industrial clusters integrate raw material sourcing, processing, design and logistics within tight geographies. This reduces cost, improves speed and enhances reliability.
India lacks comparable ecosystems at scale.
The result:
It remains a net importer of furniture from ASEAN
It has captured little of the China+1 shift in this segment
Consumer goods show a similar pattern. In toys, plastics and household items, ASEAN economies have scaled rapidly, leveraging trade integration and manufacturing coordination.
India’s presence remains limited, not due to lack of capability, but due to lack of industrial orchestration.
The Missing Middle
Taken together, these sectors reveal a structural gap.
India is competitive in high-complexity manufacturing. It is also competitive in niche segments. But it struggles in large-scale, labor-intensive production that requires:
Coordination across suppliers
Speed to market
Cost discipline at scale
This “missing middle” is where much of the China+1 shift is actually unfolding.
The Fault Lines: Why the Divergence Exists
“This is not about cheap labor. It is about system efficiency.”
Four structural variables explain the divergence.
1. Efficiency Over Demographics
India’s labor pool is large. Its manufacturing systems are less efficient.
ASEAN factories operate at scale, with standardized processes and higher throughput. India’s fragmented manufacturing structure reduces consistency and limits its ability to service large global orders.
2. The RCEP Advantage
India’s absence from the Regional Comprehensive Economic Partnership continues to shape trade outcomes.
Vietnam and Indonesia operate within a zero-tariff ecosystem that allows them to:
Import raw materials (often from China)
Process them
Export finished goods within ASEAN and beyond at minimal duty
This creates a structural loop that India cannot fully access.
It is one of the primary reasons India remains a net importer of furniture and consumer goods from ASEAN.
3. Logistics: The Cost Problem Has Been Solved The Efficiency Problem Has Not
India logistics cost: ~7.97% of GDP (2025)
ASEAN peers: ~8–9%
This is a structural shift.
According to the latest economic data, India has effectively eliminated its long-standing logistics cost disadvantage, driven by infrastructure integration and freight corridor expansion.
But a new constraint has emerged.
India remains heavily road-dependent (~65% modal share)
Trucking productivity remains low (~250 km/day vs ~700 km/day in developed markets)
The bottleneck is no longer cost. It is throughput and reliability.
For global supply chains, that distinction matters.
4. Compliance and ESG Alignment
As global sourcing shifts toward stricter ESG requirements, compliance is becoming a gatekeeper.
ASEAN exporters have moved faster in aligning with these standards. India’s compliance remains uneven, particularly among smaller manufacturers.
This affects access to premium markets and limits scaling potential in certain sectors.
The Anchor Bet: Why This Divergence Is Investable
The divergence in India’s manufacturing performance is not just an economic pattern. It is an investment signal.
A broad “India manufacturing” bet over the past three years would have produced uneven results. But a sector-specific approach focused on pharmaceuticals, chemicals or electronics would have captured the structural upside.
This is the key reframing.
China+1 is not a country-level opportunity. It is a sector-level filter.
A Mumbai-based fund manager focused on industrials put it bluntly: “If you bought the narrative, you’re disappointed. If you bought the sectors where capability matters, you’re outperforming.”
That distinction is where alpha is being generated.
What Smart Money Should Watch Next
Three things India must get right in the next 18 months.
The next phase of the China+1 shift will be determined by execution, not intent.
1. Fix the Trade Architecture
The review of ASEAN-India trade agreements is critical.
India needs:
Stricter rules of origin
Reduced non-tariff barriers
Better access for high-value exports
Without this, ASEAN will continue to outcompete India in integrated supply chains.
2. Scale Manufacturing, Not Just Incentivize It
Industrial policy must move from incentives to outcomes.
Integrated clusters particularly in textiles must deliver:
Shorter lead times
Large-scale production
End-to-end supply chain integration
Early signs from PM MITRA are encouraging, but execution at scale is the real test.
3. Solve for Speed, Not Just Cost in Logistics
India has closed the cost gap.
The next frontier is:
Faster movement of goods
Higher trucking productivity
Better multimodal integration
This is what will determine competitiveness in time-sensitive sectors.
4. Deepen Electronics Value Chains
India’s success in electronics exports is real. But sustaining it requires moving up the value chain.
That means:
Building component ecosystems
Increasing domestic value addition
Investing in design and R&D
Without this, India risks remaining a high-volume, low-margin assembly hub.
The Bottom Line
The China+1 narrative is not wrong. But it is uneven.
India is capturing share in sectors defined by complexity, compliance and capability. These gains are structural and likely to compound.
At the same time, it is losing ground in sectors defined by scale, speed and coordination where ASEAN economies have built systemic advantages.
For investors, the edge lies in recognizing that divergence early.
The opportunity in India manufacturing is real. But it is not broad-based.
It is selective. It is structural. And it is already visible in the data.
More Intelligence
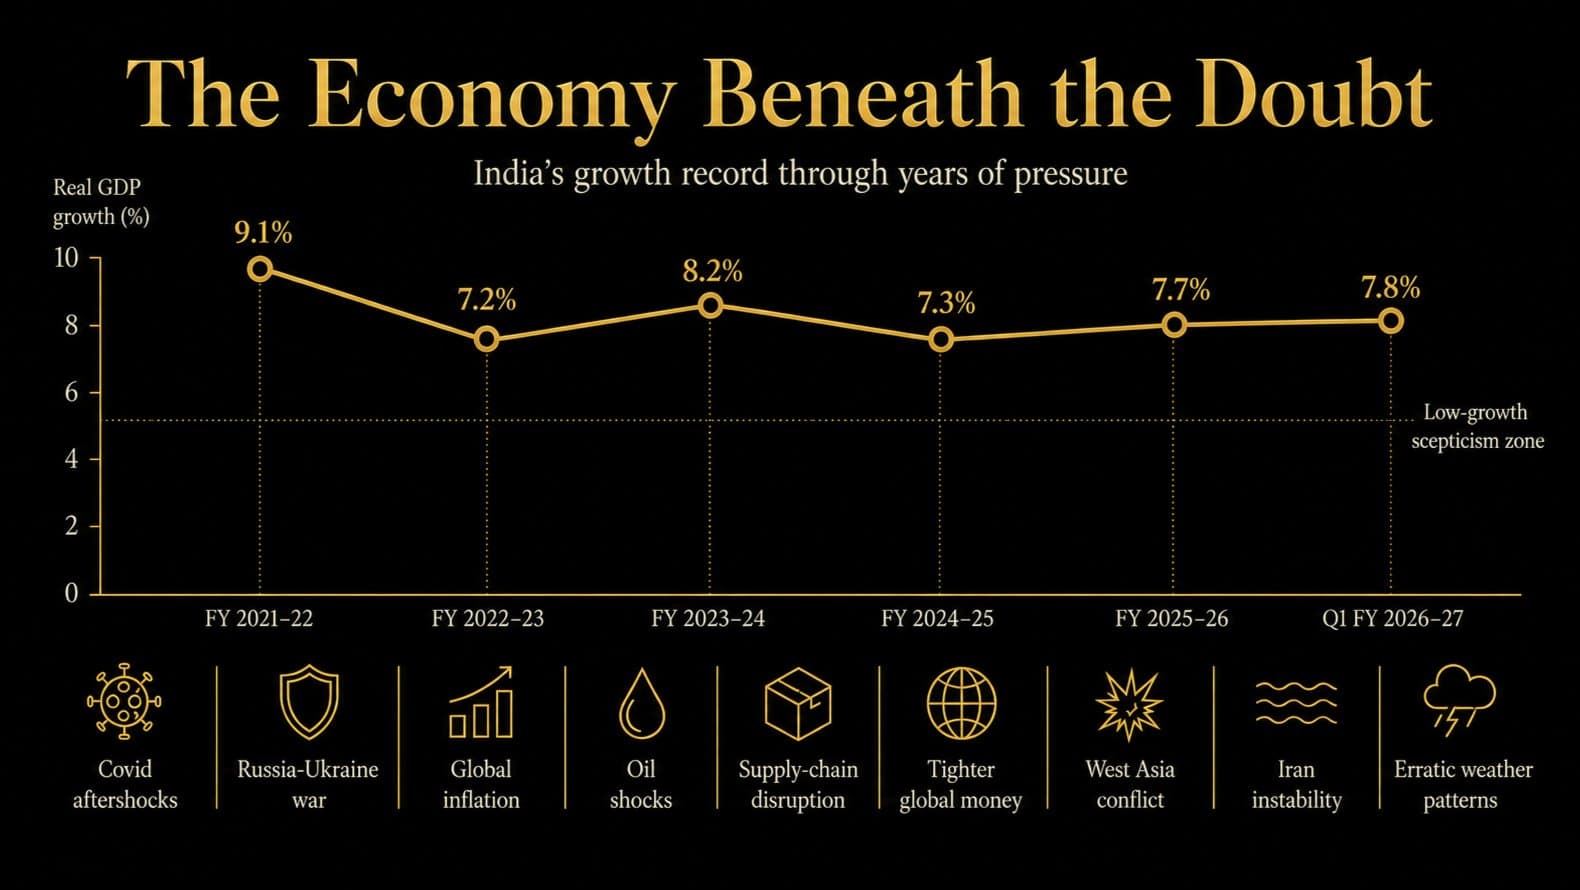
Beyond the 7.8% Headline: What the “Dead Economy” Remark Missed
When confidence in India’s post-Covid recovery was fragile, the then Chief Economic Adviser saw a 7% growth decade ahead. 5 years later, the latest 7.8% Q1 GDP print gives that call sharper context.
August 31, 2026
Can Sugar-Free Chocolate Become the Next Billion-Dollar Better-for-You Food Category?
Sugar-free chocolate, already a USD 2.6 billion global market, is projected to reach USD 4.86 billion by 2034, as better-for-you indulgence moves from niche demand toward mainstream consumption.
August 18, 2026
Industrial Cybersecurity Market: India’s Role In A USD 54.8 Billion Global Cyber-Resilience Opportunity
As factories, utilities & supply chains connect faster, India is emerging as a force in the USD 54.8 billion industrial cybersecurity market, where resilience will define the next industrial edge.
August 6, 2026